Working capital tells you if a company can pay its near-term bills. It also hints at how steady the daily grind is. In India, many firms rely on this in real life, not just in reports. Small shop owners and plant managers use it when they need to restock. They also use it to pay workers and settle bills that are due soon. Some pay suppliers early, even before customer money comes in. Others wait until the sales invoice is paid and then clear what they owe. When working capital is in good shape, cash tends to come in and go out in a calmer pattern. That helps the firm keep running even when clients delay payments. It also helps if receivables take longer than expected to close. If working capital falls below zero, stress can show up quickly. In that case, production may slow, or work can stop. Then the business may lean on costly overdrafts or cash credit. Getting the right balance matters when sales rise fast. It lowers the risk of sudden shortages later. So the money side stays more stable through the year.
What is Working Capital?
Working capital shows how well a firm can handle day-to-day needs. It looks at how much cash and near-cash the business has, compared with what it must pay soon. You get it by taking current asset management and subtracting current liabilities. The figure is what is left over. That leftover is what helps a firm keep running. It can be used for raw materials, wages, and payments to suppliers. So when cash runs short, the work does not stall. A lot of firms deal with payment lags. Buyers may wait 60 to 90 days before paying. Meanwhile, expenses often need to be covered fast.
The company still has to pay GST on time and keep enough stock. This gets tougher during peak festive seasons like Diwali. Demand jumps then, but products must be ready ahead of time. To stay liquid during slow cash-turnover periods, many Indian companies use quick funding sources. They often use Cash Credit (CC) lines and Overdraft (OD) accounts. Some also use invoice discounting through platforms such as TReDS. With this kind of working capital control, firms can meet new orders on time. They can also steer clear of costly last-minute borrowing. Over time, this helps them earn trust with banks and with suppliers.
Did you know?
RBI-supported TReDS helps Indian MSMEs sell unpaid invoices to banks after a small deduction. Instead of waiting for customer payments for months, they can get cash sooner. This supports day-to-day needs without taking a standard loan. It also tackles late payment delays, which can stall many growing businesses across India.
Why does Working Capital Matter for your Business?
Working capital is the day-to-day money that keeps a business running. It affects whether a company can pay bills when they come due, or if it runs into a cash shortage fast. In India’s fast-changing market, having enough working capital helps a firm stay flexible and steady. It can also reduce the risk of trouble when clients take longer to pay. Late payments are common in Indian trade. Many small and medium firms deal with credit periods that stretch from about 60 to 120 days. This is often true when buyers are large companies or when payments come from government groups. Even with that delay, businesses still need to pay vendors, meet payroll, and file GST software each month on time. Strong working capital helps cover the gap during these long waiting periods, so daily work does not stop just because receivables are taking longer.
India’s buyers often swing with the calendar. If a firm has cash ready, it can stock up right away. It can also ramp up output and accept bigger orders in bulk. If funds are tight, the business may miss sales. Some firms then borrow at steep rates from informal sources. That puts them behind rivals who have money on hand. Good working capital also affects trust. When you manage cash well, suppliers start to rely on you. Banks notice this too. Paying vendors on time can lead to better trade discounts. It can also bring easier payment terms. That can help lower the cost of goods sold. With steady cash and a sound working capital position, lenders view the firm as lower risk. In India, that can make it simpler to get CC limits. It can also support term loans and overdraft options. When credit is easier to obtain, the business may expand with less strain and at rates that are closer to fair.
What is the Working Capital Formula?
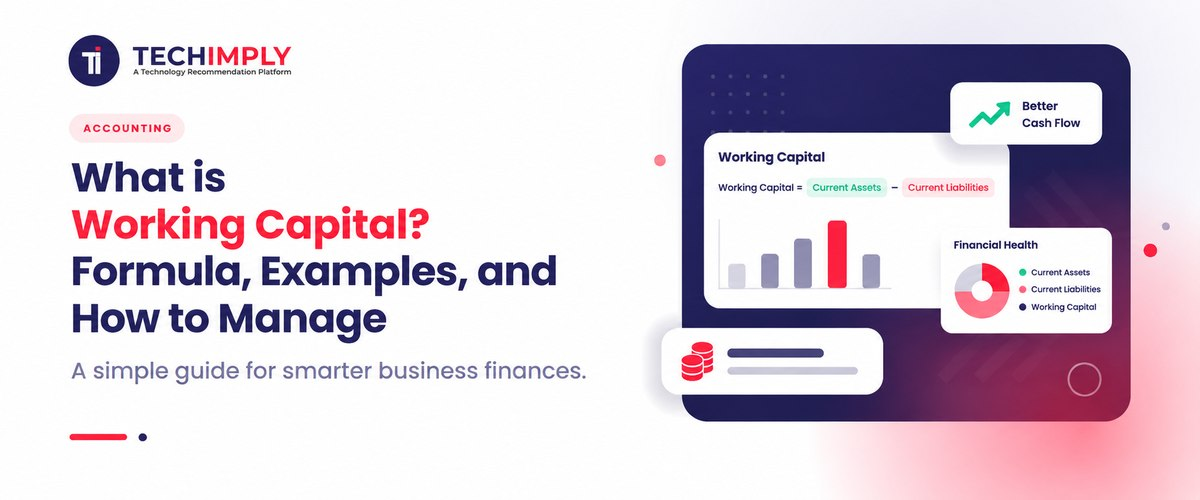
- Working capital is calculated like this: Working Capital = Current Assets minus Current Liabilities.
- Current Assets are items that should be turned into cash within a year: Common examples include cash in the bank, amounts due from customers, and inventory management that is on hand.
- Current Liabilities are the bills the business needs to settle within the next year: This can include trade bills, short-term loans, and GST or other tax amounts that are still unpaid.
- When working capital is positive, it means assets are larger than liabilities: The business can usually pay day-to-day costs and wait on some customer payments without strain.
- If working capital is below zero, then liabilities outweigh assets: This can lead to a cash pinch, and the firm might have to rely on costly overdrafts just to keep operating.
- The key idea is to watch how simple it is for the company to settle its normal bills: This also gives a clearer view of whether everyday spending can be handled without slipping on payments.
How do you Calculate Working Capital Step by Step?
- Calculate Total Current Assets: Add each current asset number together to get the total.
- Start by listing everything you can turn into cash within the next 12 months: These items are usually treated as current assets in the Indian market.
- Add cash and balances held in banks: This includes money in savings accounts, current accounts, and money in liquid fixed deposits.
- Trade receivables, also called sundry debtors: This is the money still due from buyers or distributors for sales made on credit.
- Inventory or stock-in-trade: Here you count raw materials, work in progress, and the finished items kept in the store.
- Short-term loans and advances: This includes advances made to suppliers, amounts kept as deposits with vendors, and expenses paid in advance.
- Now write Current Liabilities. These are the debts you plan to pay in the next 12 months. In India, you can include these.
- Trade payables, also called sundry creditors: These are sums owed to suppliers for goods, or to vendors for services.
- Short-term bank borrowings: These are balances taken through Cash Credit, overdraft, or demand loans meant for day-to-day business needs.
- Statutory and tax dues: Here you record money that is still pending for GST, TDS, Provident Fund, and employee state insurance detail.
- Pending operational expenses: Include unpaid utility bills, salary amounts that are still due, and rent that has piled up but remains unpaid.
- Now add up current liabilities: Put together each short-term item to reach your total current liabilities.
- Work out working capital using this rule: Working Capital = Total Current Assets - Total Current Liabilities
What does a Working Capital example look like in Practice?
|
Current Assets |
Amount (₹) |
Current Liabilities |
Amount (₹) |
|
Cash & Bank Balance: Current account balance for daily expenses |
₹15,00,000 |
Trade Payables: Dues to raw material suppliers (flour, oil, packaging) |
₹25,00,000 |
|
Trade Receivables: Unpaid invoices owed by distributors and supermarket chains |
₹45,00,000 |
Short-Term Borrowings: Utilized Cash Credit (CC) line from a public sector bank |
₹15,00,000 |
|
Inventory: Raw ingredients and packed goods stored in the central warehouse |
₹30,00,000 |
Statutory Dues & Payables: Pending monthly GST payments and employee salaries |
₹10,00,000 |
|
Total Current Assets |
₹90,00,000 |
Total Current Liabilities |
₹50,00,000 |
What Sets Positive apart from Negative Working Capital?
- Core idea: Working capital is called positive when current assets are more than current liabilities. It is called negative when current assets are below current liabilities. In simple terms, a positive number means Current Assets are higher than Current Liabilities. A negative number means the opposite, so Current Assets fall short of Current Liabilities.
- Liquidity impact: If working capital is positive, the business often has enough resources for daily spending. It may also pay vendors when due and can take more time before it must collect cash from customers.
- With negative working capital, the company lacks this cushion. Short-term bills become hard to clear.
- Operational Buffer: Positive working capital helps a business handle surprises. It can absorb slow demand or seasonal spikes without sudden stress. Negative working capital leaves little room to deal with shocks. In that case, the firm often needs quick rescue credit.
- How the firm pays for operations: If working capital is positive, operations are often funded from cash flow plus retained earnings. If working capital is negative, the company tends to lean on short-term bank support. This may include Cash Credit limits or overdraft facilities.
- Where it shows up in different sectors: Positive working capital matters a lot in heavy-spending sectors. Examples are manufacturing, textiles, and distribution, where credit periods can be long. Negative working capital can also be seen as normal in businesses that collect cash fast. Think of fast food chains or quick commerce models that get payment management right away. They may pay vendors later.
- How lenders and investors read it: Banks and other lenders often treat steady positive working capital as a sign of steadiness. It also supports the view that the firm is creditworthy. When negative working capital keeps showing up, it draws attention as a warning. It can point to solvency trouble or even insolvency risk.
How do you Manage Working Capital Effectively?
- Stop money getting trapped in items that do not sell: Use Just-in-Time stocking so goods arrive when you need them. Also do frequent stock checks. Look for pieces that sit too long and deal with them fast.
- Collect Payments faster from Customers: Set strict rules on credit. Keep payment dates and due terms clear. Send reminders on a schedule. Add a small discount when people pay early to speed up cash coming in.
- Get more time to pay Suppliers: Talk to them about longer payment windows. For example, ask to move from 30 days to 60 days. This helps keep cash in your account longer. It should still keep the supplier relationship steady.
- Track Cash Flow more Carefully: Compare money you expect to receive with what you must pay soon. Include payroll and tax bills in the view. This lets you spot a shortage before it turns into a real problem.
- Use short-term help when cash is Tight: Choose bank options that fit the gap you face. For instance, use Cash Credit limits, Overdraft accounts, or invoice discounting tools. These can cover short delays without forcing big cuts.

Pro-tip
Set up an automated process to gather invoices and use invoice discounting at the same time, so cash issues do not get started. Offer clients a small cut if they pay early. Use TReDS so invoices can be paid right away. This turns unpaid bills into money you can use now. It also helps you avoid relying on expensive loans, and it leaves you with more freedom when market chances show up fast.
Conclusion
Managing working capital is vital for sustaining daily liquidity. This can reduce the risk of an unexpected gap. It also makes it easier to see what money is left. You can line up incoming customer payments so they land near the dates you need. Many companies use online systems for these tasks now. You can track cash in and cash out, see what you still owe suppliers, and keep inventory numbers up to date. Techimply is made for those needs. Check the choices. See what each option covers. Then choose the plan that fits how you handle your day-to-day work.